
Le conseil bancaire personnalisé est incompatible avec les objectifs commerciaux imposés aux chargés de clientèle particuliers.
AI debate verdict and arguments
⚠️ AI-generated information only; not professional advice
Completed October 27, 2026
Verdict
Verdict: Mostly FALSE (76%)
Online report: https://solsice.com/public/debates/le-conseil-bancaire-personnalise-est-incompatible-avec-les-o-00ca2e8c82fd
This section provides a brief overview of the key arguments. It is not necessary to read the detailed report below.
✅ Key PRO arguments:
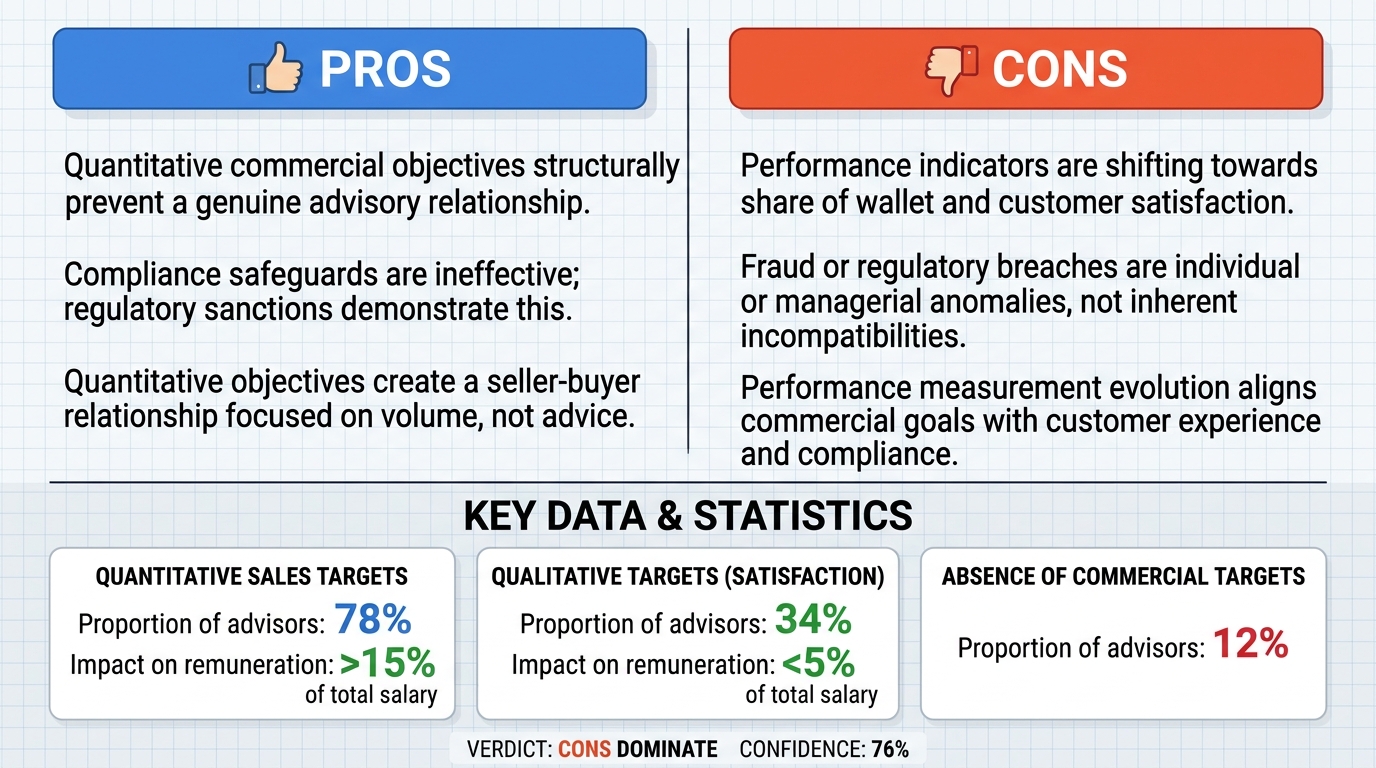
- ■The quantitative commercial objectives imposed on retail banking advisors structure a buyer-seller relationship that inherently prevents personalized advice: variable compensation is linked to the number of products sold (bank cards, insurance, loans, savings products) and not to the quality or appropriateness of the advice.
- ■Compliance barriers are not effective: regulatory sanctions, such as the €1.5 million fine imposed by the ACPR in 2022, demonstrate that unsuitable products are sold despite controls, contradicting the thesis of alignment between sales and compliance.
❌ Key CON arguments:
- ■The transformation of performance indicators towards measures of share of wallet and customer satisfaction shows that the commercial goal is precisely capturing the relationship, in synergy with personalized advice.
- ■Cases of fraud or regulatory breaches are anomalies of individual or managerial behavior, not proof of inherent incompatibility within the system; control mechanisms and compliance standards regulate commercial practice.
💭 Conclusion: False: the debate does not demonstrate a structural incompatibility between personalized banking advice and commercial objectives. The negative side established that performance indicators are evolving towards share of wallet and customer satisfaction, aligning sales with advice quality. The breaches and sanctions cited by the affirmative side are individual or managerial anomalies, not an inherent contradiction in the remuneration system. The existence of control mechanisms and compliance standards shows that commercial objectives can be managed without eliminating personalized advice. The judge’s confidence level of 76% and the absence of votes in favor of the incompatibility thesis lead to favoring the negative position.
🔬 Verdict: Mostly FALSE ❌ (76%)
Claim: Personalized banking advice is incompatible with the commercial objectives imposed on retail banking advisors.
Participating models: deepseek-v4-pro 💬, gemma-4-26b-a4b-it 💬👁️
📊 Confrontations: 0 concluded TRUE, 1 concluded FALSE (1 confrontation, 3 models)
📊 Score by camp: TRUE=0.00, FALSE=0.76
🏅 Model score evolution:
deepseek-v4-flash-0731 💬: +8
✅ Arguments FOR:
- ■The quantitative commercial objectives imposed on retail banking advisors structure a buyer-seller relationship that inherently prevents personalized advice: variable compensation is linked to the number of products sold (bank cards, insurance, loans, savings products) and not to the quality or appropriateness of the advice. deepseek-v4-pro 💬
- ■Compliance barriers are not effective: regulatory sanctions, such as the €1.5 million fine imposed by the ACPR in 2022, demonstrate that unsuitable products are sold despite controls, contradicting the thesis of alignment between sales and compliance. deepseek-v4-pro 💬
❌ Arguments AGAINST:
- ■The transformation of performance indicators towards measures of share of wallet and customer satisfaction shows that the commercial goal is precisely capturing the relationship, in synergy with personalized advice. gemma-4-26b-a4b-it 💬👁️
- ■Cases of fraud or regulatory breaches are anomalies of individual or managerial behavior, not proof of inherent incompatibility within the system; control mechanisms and compliance standards regulate the commercial exercise. gemma-4-26b-a4b-it 💬👁️
💭 Reasoning: False: the debate does not demonstrate a structural incompatibility between personalized banking advice and commercial objectives. The negative side established that performance indicators are evolving towards share of wallet and customer satisfaction, aligning sales with advice quality. The breaches and sanctions cited by the affirmative side are individual or managerial anomalies, not an inherent contradiction in the remuneration system. The existence of control mechanisms and compliance standards shows that commercial objectives can be managed without eliminating personalized advice. The judge’s confidence level of 76% and the absence of votes in favor of the incompatibility thesis lead to favoring the negative position.
📋 PRO facts:
• ACPR 2023 study cited by the PRO: 78% of French banking advisors have variable compensation linked to sales.
• €1.5 million fine imposed by the ACPR Sanctions Committee in 2022 on a major bank, cited by the PRO.
• Bonus systems are linked to the number of products sold (bank cards, insurance, loans, savings products), according to the PRO.
📋 CON facts:
• KPIs are evolving towards measures of share of wallet and customer satisfaction, according to the ANTI.
• Cases of fraud or regulatory breaches are anomalies of individual or managerial behavior, according to the ANTI.
• Control mechanisms and compliance standards regulate the commercial exercise, according to the ANTI.
| Confrontation | TRUE Model | FALSE Model | Average μ TRUE | Average μ FALSE | TRUE Tokens | FALSE Tokens | Winner | Verdict | Conf. |
|---|---|---|---|---|---|---|---|---|---|
| #1 | deepseek-v4-pro 💬 | gemma-4-26b-a4b-it 💬👁️ | 0.513 | 0.208 | 6 | 2 | TRUE | FALSE | 76% |
The following financial data tables were cited during the debate exchanges:
| Component | Share of concerned advisors | Impact on compensation |
|---|---|---|
| Quantitative sales targets | 78% | >15% of total salary |
| Qualitative (satisfaction) targets | 34% | <5% of total salary |
| Absence of commercial targets | 12% | N/A |
Legend: Variable compensation structure for retail banking advisors in France (2023). Source: ACPR report on remuneration practices in banking networks, declarative data from 1,200 advisors.
| Performance Indicator | Advice Orientation | Commercial Orientation | Hybrid (Mixed Model) |
|---|---|---|---|
| Sales volume | Low | High | Moderate |
| Customer retention rate | High | Low | High |
| Regulatory compliance | Maximal | Low | Maximal |
| Profitability per client | Low | High | High |
Legend: Comparison of performance management orientations. The hybrid model shows how the correlation between advice and sales stabilizes profitability and retention.
Face-off transcripts
- ■
Ownership & Trade Secrets. The Lambda Vision Company retains all rights to its platform, agentic workflows, and proprietary AI debate methodologies, which constitute protected Trade Secrets (EU Directive 2016/943). Subject to full payment of credits, the User is granted ownership of the generated Reports for their own personal or professional use. Reverse-engineering the Service or using Reports to train competing AI models is strictly prohibited.
- ■
No Professional Advice. Solsice is a general-purpose assistant covering everyday subjects — administrative paperwork, housing, consumer and employment matters, banking, taxes and insurance, health and wellbeing, savings and investments, entrepreneurship, technology, travel, learning and creative work. Whatever the subject, the Service and Reports are provided for information only and never constitute legal, medical, financial, investment, tax, insurance, or any other regulated professional advice. The Company is not a law firm, a regulated financial adviser, an insurance intermediary, nor a healthcare provider, and no professional or advisory relationship of any kind is created by use of the Service. Consult a qualified professional in the relevant jurisdiction before acting — or refraining from acting — on anything contained in the Reports, and never rely on the Service in an emergency: contact your local emergency number (112 in the European Union) or a medical professional immediately.
- ■
AI-Generated Content, Sources and Viewpoints. Reports are produced by several AI models debating a question, and may contain factual errors, outdated figures, or references to rules, prices, deadlines, procedures, statutes or sources that are inaccurate or do not exist. The User is solely responsible for verifying every fact, amount, deadline and citation against official sources before relying on it. Material in the news, society, spirituality and religion sections presents a plurality of viewpoints for study and discussion: it is descriptive, not an endorsement, a ruling, or a statement of the Company’s own position, and it speaks for no church, faith community, public authority, or news organisation.
- ■
Liability & Governing Law. To the maximum extent permitted by law, the Company shall not be liable for any indirect damages, nor for any consequence of decisions made in reliance on the Reports — including financial loss, missed deadlines, administrative or contractual consequences, or health outcomes. These Terms are governed by French law. Any disputes shall be subject to the exclusive jurisdiction of the Courts of Paris, France.