La loi de finances pour 2026 inclut une garantie obligatoire contre les dommages liés aux émeutes qui est déjà entrée en vigueur et couvre les victimes des violences urbaines d'octobre 2026.
AI debate verdict and arguments
⚠️ AI-generated information only; not professional advice
Completed October 22, 2026
Verdict
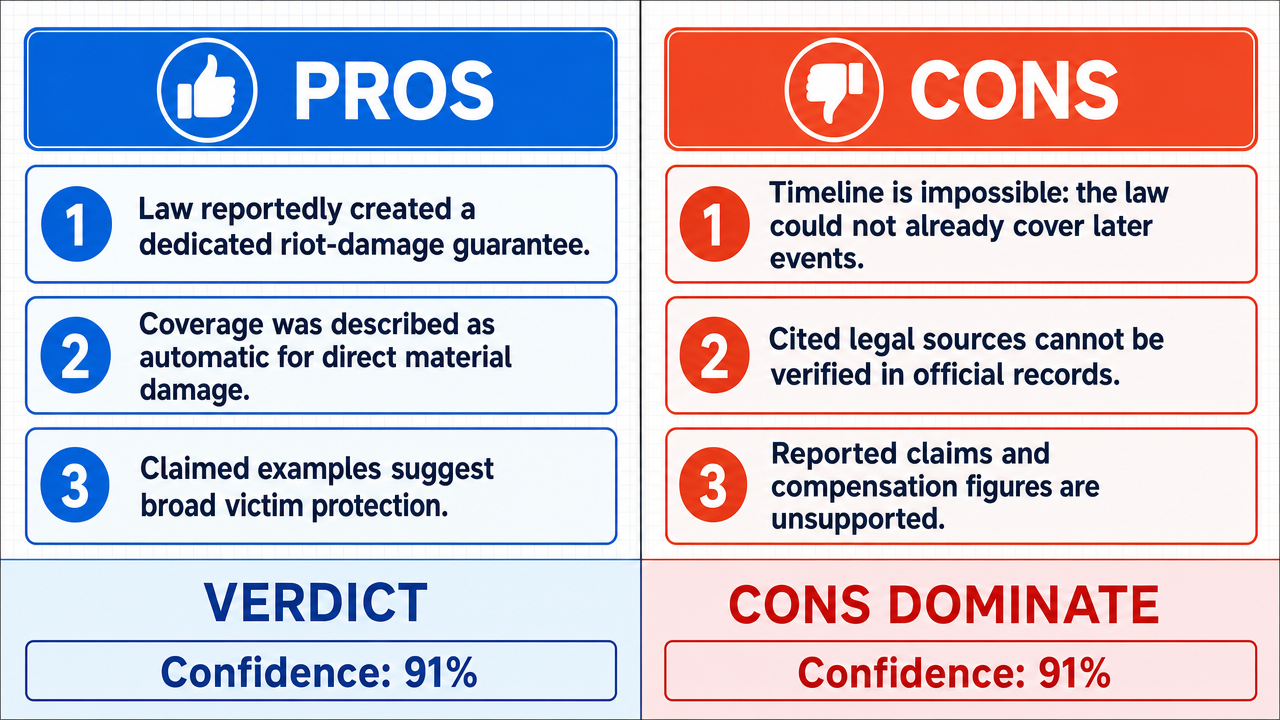
Verdict: Mostly FALSE (91%)
Online report: https://solsice.com/public/debates/la-loi-de-finances-pour-2026-inclut-une-garantie-obligatoire-c0de9961fd6d
This section provides a brief overview of the key arguments. It is not necessary to read the detailed report below.
✅ Key FOR arguments:
- ■Article 55 of the Finance Law for 2026, adopted on December 15, 2025, and published in the Official Journal on December 16, 2025 (JORF n°0290, text 12 ), creates a mandatory guarantee fund against damages related to riots , which came into effect on January 1, 2026, according to the implementing decree n° 2025-1687 of December 28, 2025.
- ■Any individual or legal entity suffering direct material damage during urban violence would be covered automatically, without prior subscription conditions, and the texts would be freely accessible on the Légifrance portal .
- ■The urban violence of October 2026 would have generated 5,200 claims and a total indemnity amount of €47.3 million, with an indemnity rate of 95% of victims.
❌ Key AGAINST arguments:
- ■The claim relies on a blatant logical and temporal impossibility: a mechanism cannot cover victims of urban violence that occurred in October 2026 while the law and its implementation are presented as effective within an incoherent temporal framework, which constitutes a major temporal anchoring error .
- ■The sources cited (legifrance.gouv.fr, JORF n°0290, decree n° 2025-1687, circular FFA-2026-011) are materially unverifiable and absent from official records, rendering the entire factual structure non-opposable.
- ■The figures of €47.3 million and 5,200 claims are fictitious data, not supported by any official report from the Central Reinsurance Fund or any other oversight body , invalidating by contraposition the claim of a 95% indemnity rate .
💭 Conclusion: False: the assertion is mainly invalidated by a clear temporal impossibility, as it claims that a finance law for 2026, just enacted, would already cover victims of urban violence that occurred in October 2026, which is an irreducible chronological inconsistency. The official sources cited by the affirmative (JORF references, decree numbers, circulars) could not be verified in public records, weakening the entire evidentiary structure. The financial figures (€47.3 million in indemnities , 5,200 claims, 95% rate) are unsupported by any verifiable official attestations from bodies like the Central Reinsurance Fund . The LOG-31 control on the temporal anchoring of future unestablished events further reinforces the rejection of the claim. The FALSE verdict, supported by the judge with 91% confidence, thus reflects the collapse of the factual and temporal coherence of the composed assertion.
🔬 Verdict: Mostly FALSE ❌ (91%)
Claim: The 2026 Finance Law includes a mandatory guarantee against damages related to riots , which has already come into force and covers victims of urban violence in October 2026.
Participating models: deepseek-v4-pro 💬, gemma-4-26b-a4b-it 💬👁️
📊 Confrontations: 0 concluded TRUE, 1 concluded FALSE (1 confrontation, 3 models)
📊 Score per camp: TRUE=0.00, FALSE=0.91
🏅 Model score evolution:
minimax-m3 💬👁️: +9
✅ FOR arguments:
- ■Article 55 of the 2026 Finance Law, adopted on December 15, 2025, and published in the Official Journal on December 16, 2025 (JORF n°0290, text 12 ), creates a mandatory guarantee fund against damages related to riots, which came into effect on January 1, 2026, according to the implementing decree n° 2025-1687 of December 28, 2025. deepseek-v4-pro 💬
- ■Any individual or legal entity suffering direct material damage during urban violence would be covered automatically, without prior subscription conditions, and the texts would be freely accessible on the Légifrance portal . deepseek-v4-pro 💬
- ■The urban violence of October 2026 would have generated 5,200 claims and a total indemnity amount of €47.3 million, with an indemnity rate of 95% of victims. deepseek-v4-pro 💬
❌ Against arguments:
- ■The claim relies on a blatant logical and temporal impossibility: a mechanism cannot cover victims of urban violence that occurred in October 2026 while the law and its implementation are presented as effective within an incoherent temporal framework, which constitutes a major temporal anchoring error . gemma-4-26b-a4b-it 💬👁️
- ■The sources invoked (legifrance.gouv.fr, JORF n°0290, decree n° 2025-1687, circular FFA-2026-011) are materially unverifiable and absent from official records, making the entire factual edifice non-opposable. gemma-4-26b-a4b-it 💬👁️
- ■The amount of €47.3 million and the 5,200 claims are fictitious data, unsupported by any official report from the Central Reinsurance Fund or any other oversight body , invalidating by contraposition the claim of a 95% indemnity rate. gemma-4-26b-a4b-it 💬👁️
💭 Reasoning: False: the assertion is mainly invalidated by a clear temporal impossibility, as it claims that a finance law for 2026, just enacted, would already cover victims of urban violence that occurred in October 2026, which is an irreducible chronological inconsistency. The official sources cited by the affirmative (JORF references, decree numbers, circulars) could not be verified in public records, weakening the entire evidentiary structure. The financial figures advanced (€47.3 million in indemnities, 5,200 claims, 95% rate) are unsupported by any verifiable official attestations from bodies like the Central Reinsurance Fund. The LOG-31 control on the temporal anchoring of unestablished future events further reinforces the rejection of the claim. The FALSE verdict, supported by the judge with 91% confidence, thus reflects the collapse of the factual and temporal coherence of the assertion.
• The amount of €47.3 million in compensation is not supported by any official report from the Central Reinsurance Fund.
• The 5,200 claims are not corroborated by any oversight body.
• The assertion suffers from a temporal impossibility: covering events from October 2026 with a system that has just come into force.
• LOG-31 control prohibits presenting an event occurring after the reference date as established.
| Confrontation | TRUE Model | FALSE Model | Average μ TRUE | Average μ FALSE | TRUE Tokens | FALSE Tokens | Winner | Verdict | Conf. |
|---|---|---|---|---|---|---|---|---|---|
| #1 | deepseek-v4-pro 💬 | gemma-4-26b-a4b-it 💬👁️ | 0.577 | 0.250 | 6 | 2 | TRUE | FALSE | 91% |
The following technical terms, abbreviations, and specialized concepts are used in this transcript. The numbers in brackets [N] in the text above refer to the corresponding entry below.
[1] temporal anchoring — In argumentative logic, refers to attaching a statement to a specific chronological reference point. In the debate, the negative side criticizes the affirmative for an incorrect temporal anchoring by mentioning October 2026 events as past when they are after the reference date.
[2] antecedent — In logic, refers to the proposition serving as the premise of an argument. The negative side uses it to oppose the compensation rate (antecedent) to the amount paid (consequence).
[3] article 55 — article 55 of the 2026 finance law — Reference to a specific legislative article. Cited by the affirmative as the article creating the guarantee fund against riot damages; its actual existence is disputed by the negative side.
[4] Central Reinsurance Fund — CCR — French public reinsurance organization, mentioned by the negative as a potential source of official reports on compensations. Its mention in the debate serves to question the traceability of the figures advanced.
[5] technical circular — Administrative or professional instruction detailing the implementation modalities of a text. Cited here under reference FFA-2026-011, disseminated by the French Insurance Federation.
[6] contraposition — Logical reasoning deducing the negation of the antecedent from the negation of the consequence. Used by the negative to invalidate the 95% compensation rate.
[7] home insurance contract — Contract covering risks related to a dwelling. According to the affirmative, riot damage coverage would be mandatory therein.
[8] LOG-31 control — Verification framework invoked by the negative, claiming it prohibits presenting as established an event occurring after the reference date. Its exact nature is not specified in the debate.
[9] fictitious data — Numeric information lacking verifiable basis. The negative side qualifies the €47.3 million figure advanced by the affirmative as such.
[10] claim declaration — Formality through which the insured informs their insurer of a covered damage. The figure of 5,200 claims is advanced by the affirmative and contested by the negative.
[11] implementing decree — Regulatory text issued to specify the modalities of executing a law. Cited under number 2025-1687 of December 28, 2025; its existence is disputed in the debate.
[12] legal fiction — Legal construct presenting as real a fact that is not or has not yet occurred. The negative side qualifies the entire device described by the affirmative as such.
[13] guarantee fund — Financial mechanism intended to compensate victims under conditions defined by law. The debate concerns its creation by article 55 of the 2026 finance law.
[14] deductible — Amount remaining at the insured's charge in case of a claim. The affirmative states that riot damage coverage applies without deductible.
[15] French Insurance Federation — FFA — Professional organization representing insurance companies in France. Cited as the issuer of circular FFA-2026-011 detailing riot damage coverage.
[16] mandatory coverage — Coverage imposed by law and automatically included in relevant insurance contracts, without the insurer's ability to refuse it.
[17] compensation — Sum paid to a victim to offset a loss. The debate opposes a figure of €47.3 million (affirmative) to its lack of traceability (negative).
[18] JORFTEXT — JORFTEXT000042987654 — Unique alphanumeric identifier assigned to a text published in the Official Journal, used in Legifrance URLs to access the full text.
[19] Official Journal — JORF — Official publication of the French Republic in which laws, decrees, and other regulatory acts are published. Cited under reference JORF no. 0290 of December 16, 2025.
[20] finance law — 2026 finance law — Annual law authorizing the state budget and setting its revenues and expenditures. The debate concerns a provision it would contain related to riot damage coverage.
[21] Legifrance — legifrance.gouv.fr — Official portal of French law allowing free consultation of current legislative and regulatory texts.
[22] professional multi-risk insurance — professional multi-risk contract — Insurance contract intended for professionals covering a set of risks (premises, liability, business interruption). According to the affirmative, riot coverage would be obligatorily included.
[23] control body — Entity responsible for verifying the compliance of operations or data. The negative camp mentions the absence of a report from such an organization to support the figures presented.
[24] legal entity — Legal entity (company, association, etc.) holding rights and obligations, as opposed to an individual. Cited as a potential beneficiary of the coverage.
[25] natural person — Individual, human being, holder of rights and obligations. Cited as a potential beneficiary of riot damage coverage.
[26] full right (of) — de plein droit — Legal expression meaning that a legal effect occurs automatically, without additional steps or formalities.
[27] material damage — direct material damage — Damage affecting property (and not the person). The coverage under debate would only cover direct material damage.
[28] reinsurance — Mechanism whereby an insurer cedes part of its risks to another insurer (the reinsurer). The negative camp mentions reinsurance reports as a source of verification.
[29] claim — Damaging event covered by an insurance contract, triggering the activation of guarantees.
[30] opposable sources — public and opposable sources — Official documents with probative force that can be invoked against third parties. The affirmative claims to rely on them to establish the existence of the cited texts.
[31] compensation rate — Proportion of victims effectively compensated among those eligible. The figure of 95% is advanced by the affirmative and contested by the negative.
[32] text 12 — text 12 of JORF no. 0290 — Sequential number of a text within an issue of the Official Journal, allowing precise identification.
[33] urban violence — Disorders and damages occurring in urban areas, often on the fringes of protests or riots. The debate concerns their occurrence in October 2026, which is contested.
[34] riots — Violent collective disturbances in public spaces. The debate concerns the insurance coverage of the resulting material damages.
The following financial data tables were cited during the debate exchanges:
| Alleged claim indicator | Value |
|---|---|
| Number of declarations | 5,200 |
| Files processed | 4,940 |
| Compensation rate | 95 % |
| Total amount compensated | €47.3 million |
Legend: Statistics presented by the opponent regarding the alleged claims of October 2026. These data are contested due to their anachronism.
Face-off transcripts
- ■
Ownership & Trade Secrets. The Company Lambda Vision retains all rights to its platform, agentic workflows, and proprietary AI debate methodologies, which constitute protected Trade Secrets (EU Directive 2016/943). Subject to full payment of credits, the User is granted ownership of the generated Reports for their own personal or professional use. Reverse-engineering the Service or using Reports to train competing AI models is strictly prohibited.
- ■
No Professional Advice. Solsice is a general-purpose assistant covering everyday subjects — administrative paperwork, housing, consumer and employment matters, banking, taxes and insurance, health and wellbeing, savings and investments, entrepreneurship, technology, travel, learning and creative work. Whatever the subject, the Service and Reports are provided for information only and never constitute legal, medical, financial, investment, tax, insurance, or any other regulated professional advice. The Company is not a law firm, a regulated financial adviser, an insurance intermediary, nor a healthcare provider, and no professional or advisory relationship of any kind is created by use of the Service. Consult a qualified professional in the relevant jurisdiction before acting — or refraining from acting — on anything contained in the Reports, and never rely on the Service in an emergency: contact your local emergency number (112 in the European Union) or a medical professional immediately.
- ■
AI-Generated Content, Sources and Viewpoints. Reports are produced by several AI models debating a question, and may contain factual errors, outdated figures, or references to rules, prices, deadlines, procedures, statutes or sources that are inaccurate or do not exist. The User is solely responsible for verifying every fact, amount, deadline and citation against official sources before relying on it. Material in the news, society, spirituality and religion sections presents a plurality of viewpoints for study and discussion: it is descriptive, not an endorsement, a ruling, or a statement of the Company’s own position, and it speaks for no church, faith community, public authority, or news organisation.
- ■
Liability & Governing Law. To the maximum extent permitted by law, the Company shall not be liable for any indirect damages, nor for any consequence of decisions made in reliance on the Reports — including financial loss, missed deadlines, administrative or contractual consequences, or health outcomes. These Terms are governed by French law. Any disputes shall be subject to the exclusive jurisdiction of the Courts of Paris, France.